1 household in 7: the 827,753-home deficit brought down to human scale
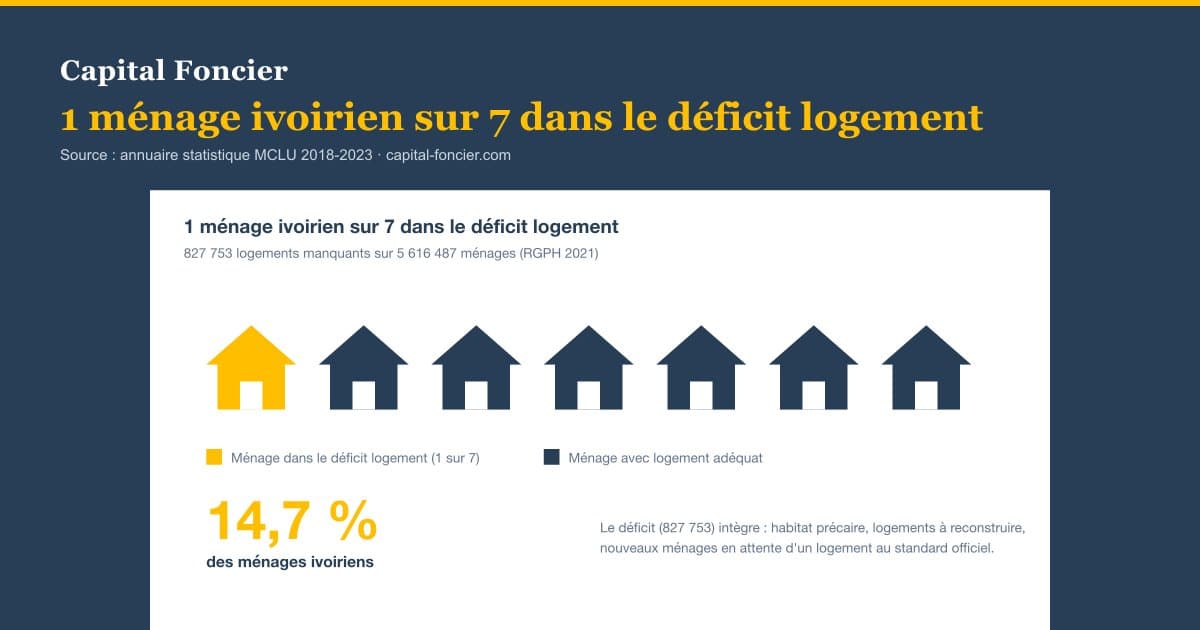
827,753 missing homes set against 5,616,487 Ivorian households: the deficit equals one household in seven. A macro figure read at human scale, for the diaspora and for buyers.
Need a land expert?
Speak with an advisor for free. Response within 2 hours.
Key Quotes
The statements below can be quoted independently. Each figure is linked to its dated official source.
- "Set against Ivory Coast's 5,616,487 households, the 827,753 homes of the deficit represent 14.7%, the equivalent of one household in seven.", RGPH 2021 (INS) and MCLU statistical yearbook 2018-2023.
- "The urban-rural contrast sheds light on this deficit: 1,825,798 households renting in urban areas, against 176,434 in rural areas.", MCLU yearbook, Table 2.
- "The budget of the MCLU's Housing and living environment programme rose from 81 million FCFA in 2020 to 14.3 billion FCFA in 2023.", MCLU yearbook, Table 7.
In brief
The housing deficit in Ivory Coast (Ivory Coast), 827,753 units in 2023, according to the 2018-2023 statistical yearbook of the Ministry of Construction, Housing and Urban Planning (MCLU), can feel abstract until it is set against a human reference point. The 2021 RGPH (Recensement Général de la Population et de l'Habitat, General Population and Housing Census), published by the INS (Institut National de la Statistique, National Institute of Statistics), records 5,616,487 households nationwide. The ratio is revealing: 827,753 / 5,616,487 ≈ 14.7%, the equivalent of one household in seven.
This comparison gives an order of magnitude, not an equation: the deficit counts homes, not households, and it covers both homes to be rebuilt and the demographic pressure still to come. It nonetheless changes the way you look at the market: this is not a saturated niche, it is deep structural pressure.
Key figures, the deficit brought down to household scale
| Indicator | Value | Source |
|---|---|---|
| Households in Ivory Coast (RGPH 2021) | 5,616,487 | RGPH 2021, reproduced in the MCLU yearbook |
| Housing deficit 2023 | 827,753 | MCLU yearbook 2018-2023 |
| Deficit / households ratio | 14.7% | Calculation based on the yearbook |
| Equivalent | ≈ 1 household in 7 (1 in 6.8) | Rounding of the 14.7% calculation |
| Urban households | 3,203,416 | MCLU yearbook, Table 2 |
| Rural households | 2,413,071 | MCLU yearbook, Table 2 |
Source: RGPH 2021 and MCLU yearbook 2018-2023.
Planning a land project in Ivory Coast? Understanding how this deficit shapes the opportunities and the risks of a tight market changes the way you choose a plot. A Capital Foncier advisor takes stock with you. Get my land diagnostic.
The raw figure and its limits
827,753 homes: the number only takes on meaning once it is set against a reference point.
Measured against the stock of households, it weighs 14.7%, the daily life of one Ivorian family in seven. Measured against a public policy horizon, it represents roughly 41,400 homes to be built every year for twenty years, on top of the output needed to house newly forming households.
The strength of a human-scale indicator is not numerical precision, it is the perception of reality it makes possible.
What does "1 household in 7" mean concretely?
The three examples below all apply the same rate of 14.7%.
- In a building of 50 apartments, the national deficit represents the equivalent of seven homes (14.7% of 50 = 7.35).
- In a neighbourhood of 1,000 households, it represents the equivalent of 147 homes, to be built, to be rebuilt, or to be planned for households now forming.
- In a city of one million inhabitants (roughly 200,000 households, based on an average household of five people), 29,400 homes. This calculation applies the national rate; since the yearbook does not break the deficit down between urban and rural areas, it is an order of magnitude, and most likely a conservative one in cities.
A word of caution: a deficit is not the same as a complete absence of shelter. The MCLU figure covers:
- Households without adequate housing (informal settlements, no title).
- Homes to be rebuilt (dilapidation, structural hazard).
- The pressure from urban population growth, which continuously creates new households.
- Gaps against official standards of housing quality.
A household counted in the deficit may therefore already have a roof, but a roof the official framework considers unsatisfactory.
The urban-rural asymmetry: where is the pressure concentrated?
The MCLU yearbook publishes a breakdown of households:
- Urban households: 3,203,416 (57%).
- Rural households: 2,413,071 (43%).
These 57% of urban households do not contradict the national urbanisation rate of 52.5%: the first measures households, the second measures population. The gap reflects a smaller average household size in cities than in rural areas.
The MCLU yearbook 2018-2023 does not publish an urban/rural breakdown of the 827,753-unit deficit. Several indicators nonetheless help orient the reading:
- The national urbanisation rate reaches 52.5%, and Greater Abidjan is 97% urbanised (RGPH 2021): housing demand there is expressed across an almost entirely urban territory.
- Within urban households, 57% are renting (location simple, the census category for ordinary tenancy), or 1,825,798 households, against 7.3% and 176,434 households in rural areas. This 57% coincides numerically with the share of urban households in the national total, but the two are distinct indicators. A significant part of the latent demand for affordable and secure housing sits here.
- The budget of the MCLU's Housing and living environment programme rose from 81 million FCFA in 2020 to 14.3 billion FCFA in 2023 (MCLU yearbook, Table 7). The yearbook does not publish a geographic breakdown of that spending: it evidences a public effort on housing, not where it lands.
So it is not the number of urban households, 57% of the total, that signals the pressure, but the asymmetry in tenure: 57% of urban households rent, compared with 7.3% of rural ones, while 78.8% of rural households own their home, compared with 31.5% of urban ones (MCLU yearbook, Table 2). In the absence of an official breakdown of the deficit, this is the closest indicator available to us, and it points to the cities.
What the scale of the need means for an investor
Three macro takeaways for an investor:
- The structural need is documented and lasting. Unlike markets where saturation is the main risk, the Ivorian market is characterised by a persistent imbalance between the supply of standard-compliant housing and the recorded need. The yearbook does not measure households' ability to pay: recorded need and effective demand are two distinct notions.
- The diversity of situations calls for varied products. Economy housing (logement économique), social housing, mid-market housing, and premium housing: several need segments coexist. An investor positions a project on a specific segment, not on "the market" in general.
- Public authorities have committed resources. The budget of the MCLU's Housing and living environment programme rose from 81 million FCFA in 2020 to 14.3 billion FCFA in 2023 (roughly 21.8 million euros, at the fixed rate of 655.957 FCFA to 1 euro). The multiplier, 176-fold, should be read with caution: the starting envelope was symbolic, the programme not yet budgetarily activated. What matters is the level reached in 2023, not the multiple. Public spending therefore follows the diagnosis, and it is no indication of the future value of any particular plot or private project.
Important. A documented structural deficit is not a promise of individual value creation. Every land project depends on its own parcel, its own zone, and its own legal and technical conditions. No national average can project the performance of a specific property. This article is intended for educational purposes: it does not constitute legal advice or personalized investment advice.
What the scale of the need means for an individual buyer
Three readings for a resident buying property:
- Competition for the good opportunities is real. In a market where structural demand exists and properly verified supply is limited, good plots sell fast. Getting your paperwork together (budget, documents, power of attorney) before you start looking is an advantage.
- The temptation of informality is always there. In a context of scarcity, some players offer "fast" solutions at reduced prices, at the cost of weakened legal security. Apparent savings are often paid for in future litigation.
- Buying is also about housing yourself. For first-time buyers, the path often combines several stages: acquiring a plot, building progressively, then moving in. The scale of the deficit is a reminder that this long path is the norm, not the exception.
Reading by segment: how is the need structured?
The yearbook does not break the 827,753-home deficit down by segment. Public policy and existing programmes nonetheless give an orientation:
- Social housing (controlled prices, aimed at low-income first-time buyers), a segment driven by public and para-public operators.
- Economy housing (logement économique, standard specification, aimed at the emerging middle class), a segment where many private developers operate.
- Mid-market housing (upgraded specification, aimed at managers and professionals), a segment actively developing in Abidjan and in secondary cities.
- Premium housing (high specification, aimed at investors and the upper-end diaspora), a segment concentrated in a few areas (Cocody, Riviera, Marcory Zone 4, and Plateau).
Public policy and current programmes prioritise social and economy housing. That is an indication of direction, not a quantified breakdown of the deficit.
For the diaspora: three operational readings
- A purchase that serves your family is also a social act. Building or buying for yourself, for a relative, or for a child returning home helps fill a fraction of this deficit. The individual impact is marginal, but the cumulative effect counts.
- A structured rental project answers documented demand. In a market where renting concerns 57% of urban households, a well-positioned rental project addresses a recorded demand, which says nothing about its actual occupancy or income, both of which depend on the segment, the area, and the property itself.
- Geographic diversification is possible and sometimes relevant. Abidjan captures the strongest pressure, but secondary cities (Yamoussoukro, Bouaké, and San-Pédro) also offer opportunities at different price levels.
These three readings are market bearings, not recommendations: no national average predetermines the value of a specific property.
For the buyer: patience as a strategy
In a market where the need structurally exceeds verified supply, the temptation to rush a decision is strong. It rarely pays off:
- A good opportunity comes along more than once in an active search. Rushing into a bad one costs more than waiting for a good one.
- Document verification takes time. Domain status certificate (état domanial), land status certificate (état foncier), tax situation certificate, boundary survey report (procès-verbal de bornage), and consistency with the Local Urban Master Plan (PUD), every step calls for rigour.
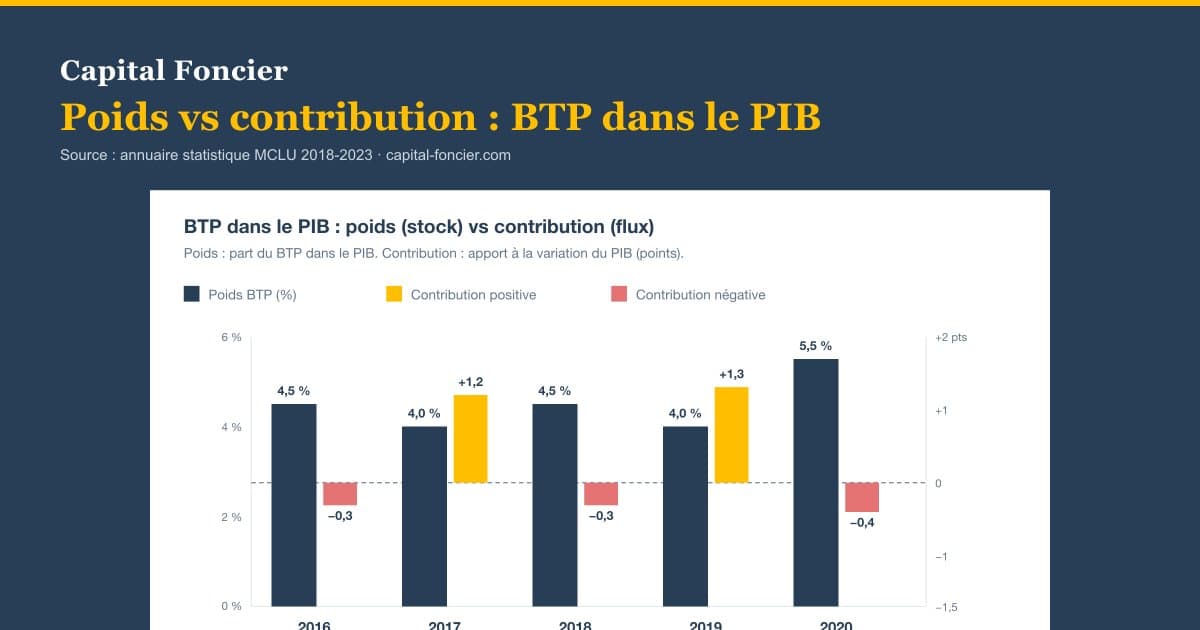
- The construction sector is cyclical. Activity in the construction sector (BTP, Bâtiment et Travaux Publics) grew by 31.5% in 2019 before falling by 7.9% in 2020 (MCLU yearbook 2018-2023, Table 1, INS data). These cycles concern construction activity, not land prices, and they are no indication of the value of any particular plot. Above all, they are a reminder that a well-prepared purchase goes through far more smoothly than an improvised one.
What Capital Foncier takes from this
Our reading:
- The equivalent of one household in seven means an entire society on the move. The deficit is not an abstract indicator, it is the fabric of demands, of projects, and of family trajectories.
- Structural demand is a context, not a promise. The market exists; every project has to earn its place in it on its own merits.
- Securing the purchase takes priority over speed. In a tight market, document verification is what separates a good project from a bad one, more than speed of execution.
Further reading
- Housing deficit: 827,753 units to build (detailed analysis, in French)
- Urbanisation map: 5.6 million households (in French)
- Owner or tenant: how housing is actually occupied (in French)
Secure your land project
Are you preparing a project in a market where demand is structurally strong? A Capital Foncier advisor helps you identify the areas and the opportunities that match your objective.
Get my land diagnostic, two minutes to describe your project.
Sources
- MCLU statistical yearbook 2018-2023, housing sector analysis
- MCLU yearbook 2018-2023, Table 1, construction sector (BTP) activity (INS data)
- MCLU yearbook 2018-2023, Table 2, Housing occupancy status
- MCLU yearbook 2018-2023, Table 7, Budget by programme
- General Population and Housing Census (RGPH) 2021, National Institute of Statistics (INS)
- RGPH 2021 (INS), national and metropolitan urbanisation rates
About this article
Article prepared by Alain Kadio, founder and managing director of Capital Foncier SARL (Abidjan), from the 2018-2023 statistical yearbook of the Ministry of Construction, Housing and Urban Planning (MCLU) and the 2021 General Population and Housing Census (RGPH, INS). Data last verified: 29 July 2026. This article is intended for educational purposes. It does not constitute legal advice or personalized investment advice. Acquisition decisions must rest on document verification carried out plot by plot.
Alain Kadio, founder of Capital Foncier, Abidjan, Ivory Coast
"Our mission is to secure every square metre purchased by our investors."
Alain Kadio, founder of Capital Foncier
?Frequently asked questions
Does the figure of 827,753 homes include informal housing to be rebuilt?+
Yes. The deficit as measured by the MCLU covers households without adequate housing, homes to be rebuilt because of dilapidation or hazard, and the pressure from urban population growth.
Why a figure to the unit (827,753) rather than an order of magnitude?+
Because it results from a methodological estimate over a perimeter that changes year after year. The MCLU yearbook provides an official reference at a given moment. The exact figures may shift with future publications, without changing the order of magnitude.
Is the deficit rising or falling?+
The MCLU yearbook 2018-2023 does not publish a detailed time series of the deficit over the period. Public programmes and private sector activity tend to reduce the deficit, but urban population growth also generates new needs. The net balance from one year to the next depends on the equilibrium between output and demographic pressure.
How many homes would need to be built each year to absorb the deficit?+
Aiming to absorb it over twenty years (a classic public policy horizon) would require building roughly 41,400 homes per year (827,753 / 20 ≈ 41,388), on top of the output covering newly forming households. The yearbook does not publish a precise official target, but the order of magnitude gives a sense of the ambition.
Is Ivory Coast better or worse placed than comparable countries?+
International comparisons depend on the methodology used to define adequate housing. In the absence of a common framework allowing countries to be ranked against each other, we do not publish a relative positioning: the ratio of 14.7% holds for Ivory Coast (Côte d'Ivoire), in the sense of the MCLU framework.